Start with the contract, not the mover's brochure
Get the quote and carriage contract before accepting the job. Check that they record both addresses, dates, access issues, services, price, cancellation or delay terms, who will pack, and whether a subcontractor or storage facility will handle your belongings. Ask which legal business is the contracting carrier and who will physically carry each stage.
New Zealand's carriage rules allow four contract types: owner's risk, declared value risk, declared terms and limited carrier's risk. Consumer Protection explains each type and says carriage contracts must be in writing. If there is no written contract, Consumer Protection says the goods travel at limited carrier's risk. The label matters because it changes what the carrier may have to pay.
Owner's risk can leave a serious gap
Under the Contract and Commercial Law Act, an owner's-risk carrier is generally not liable for accidental loss or damage and remains liable where it intentionally causes the loss or damage. Consumer Protection also notes that the Consumer Guarantees Act may provide a separate reasonable-care-and-skill claim in some circumstances. That route can require proof of the mover's failure, so owner's risk should not be read as replacement cover.
Ask what protection you would actually have if a box were dropped, furniture were scraped or the truck were involved in a crash. Compare the answer with your contents policy before accepting the contract, and get legal advice if a high-value move depends on how the two laws interact.
Limited carrier's risk is not full replacement cover
Under limited carrier's risk, the carrier can be liable under the Act, but a statutory limit applies. Consumer Protection currently states a maximum of $2,000 for each unit of goods. A separately accepted item or package may be a unit, so ask the mover to explain how the inventory and boxes will be recorded. The Contract and Commercial Law Act carriage provisions contain the legal detail.
If an item is worth much more than the limit, discuss declared value or separate insurance before it is loaded. Do not assume a verbal assurance changes the written contract.
Check your contents policy across the whole journey
A contents policy may cover a move, but the conditions and limits vary. Consumer Protection recommends checking the policy wording and asking the insurer when anything is unclear. Get written answers for packing, loading, transit, unloading and any overnight or self-storage period.
Tell the insurer who is packing. Ask specifically about self-packed cartons, fragile items, jewellery, artwork, collections and other high-value belongings. Confirm the excess, evidence needed for a claim and whether the mover must meet any policy condition. Carrier liability and contents insurance are separate protections, and neither should be assumed to fill every gap in the other.
Before choosing a mover
- Give every mover the same inventory and access information.
- Get the quote and carriage contract in writing.
- Identify the liability type and any cap or exclusion.
- Ask who packs fragile and high-value items.
- Confirm whether subcontractors or storage facilities will be used.
- Ask your insurer about packing, transit, unloading and storage cover.
- Photograph valuable items and their condition before packing.
- Keep receipts, valuations and serial numbers for important belongings.
Packing decisions need to be recorded
Consumer Protection notes that a carrier may have a defence when loss or damage results directly from goods not being properly prepared or packed. If you pack, follow the mover's written requirements and label fragile cartons. If the mover packs, make sure that service appears on the quote and inventory. Ask both the mover and insurer how they treat owner-packed boxes.
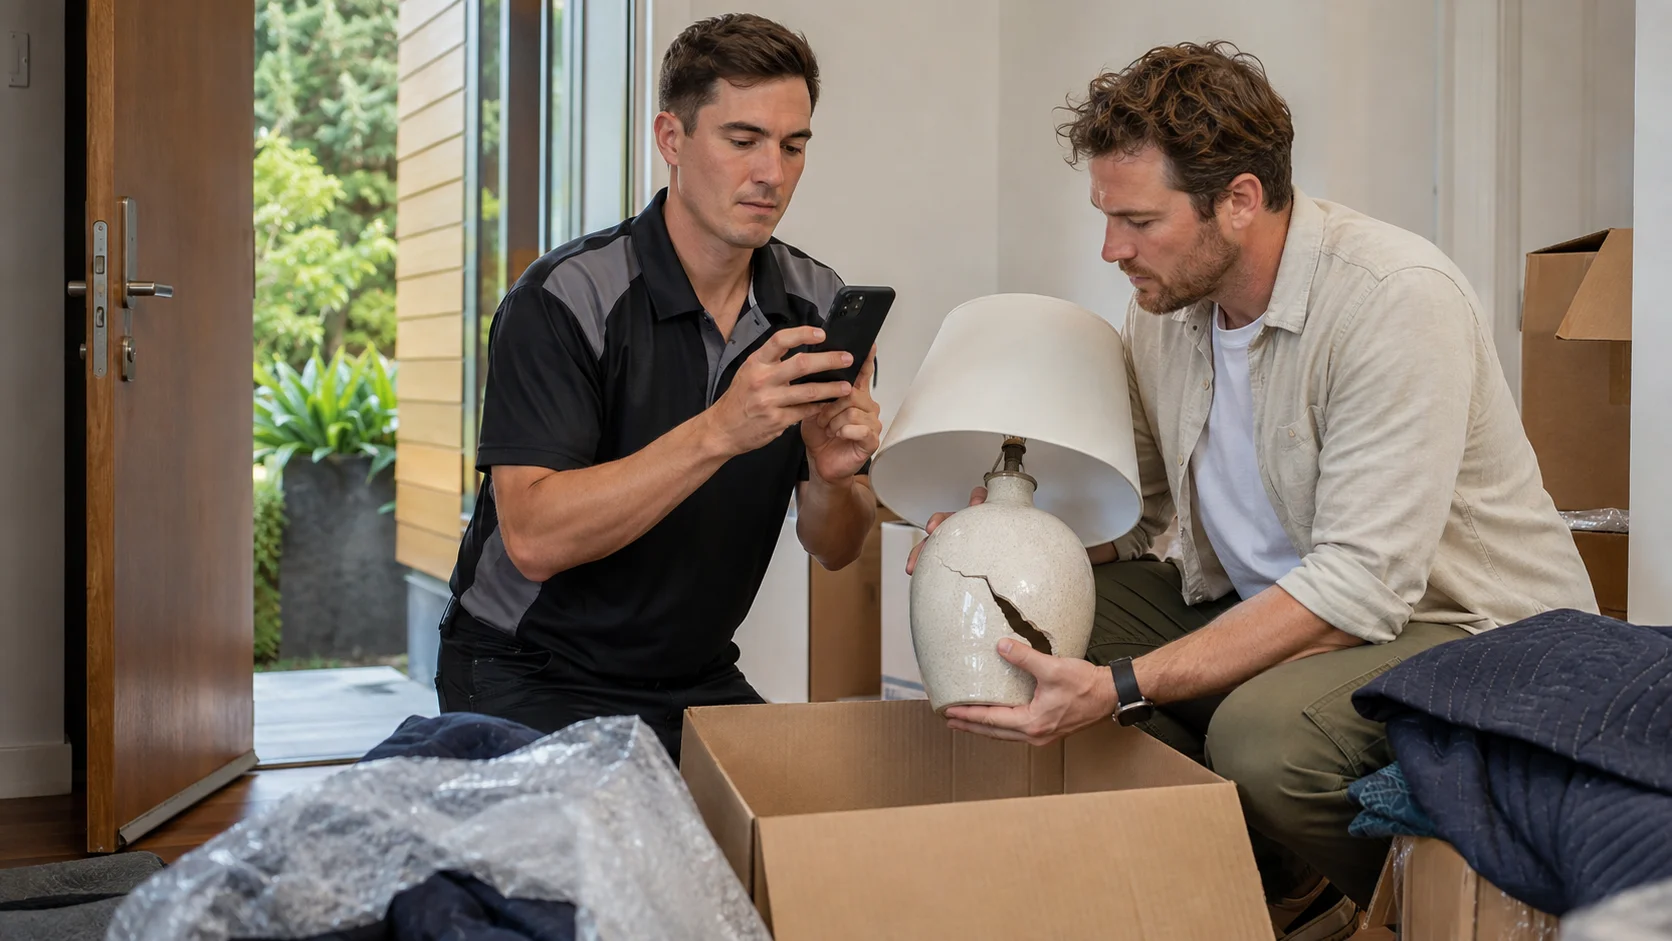
If something is missing or damaged, act promptly
- Photograph the item, damage and packaging before moving or discarding anything.
- Note the inventory or box number and when you discovered the problem.
- Notify the contracting mover, any actual carrier and the insurer in writing.
- Keep the contract, quote, inventory, receipts, valuations and messages together.
- Wait for the insurer's instructions before arranging a repair or disposal.
The Act sets different notice periods: generally 30 days for a claim against the contracting carrier and 10 days for a claim against an actual carrier. A contract or policy can also require quick action. Notify all relevant parties immediately rather than trying to decide which deadline applies on your own.
State what happened, what is missing or damaged, when it was found and what outcome you seek. Consumer Protection's complaints guidance recommends putting the issue and requested remedy in writing and keeping supporting evidence. If the business does not resolve it, the next forum depends on the contract, amount and parties involved.
Connect the practical plan
Put the mover, insurance and storage questions beside your dates
Use the moving-cost guide to compare like-for-like quotes, then add the chosen mover, insurance confirmations and any gap between homes to your private Selling Plan.
Frequently asked questions
Is a mover automatically liable for the full value of damaged goods?
No. Liability depends on the written contract type, statutory rules and any agreed value or terms. Check the contract and your own insurance before moving day.
What happens if there is no written carriage contract?
Consumer Protection says the goods are treated as travelling at limited carrier's risk. Get legal advice if the paperwork or a claim is unclear.
Are self-packed boxes covered?
Not necessarily. Ask both the mover and insurer. Poor preparation or packing can affect carrier liability, and insurance policies may have separate conditions.
Should I photograph everything?
A practical room-by-room record is useful. Prioritise valuable, fragile or hard-to-replace items and keep receipts, valuations or serial numbers where available.
Official sources
Reviewed 21 August 2026. Contracts and policies vary, so obtain advice on your actual documents when the financial consequence matters.
Keep the public guide
Share the article or save a private PDF.
No account is needed to read or share this guide. A private seller account is only needed to create its personalised A4 PDF.
Optional seller account
Take the useful work to another device.
Sign in to access the planning information saved to your account on another device and save personalised guide PDFs. Your saved plan and calculator results are not included in introduction requests.